BRSR and BRSR Core Guide: What SEBI Requires and How to Get Ready for Assurance
BRSR and BRSR Core in plain language, updated for SEBI’s March 2025 changes and the January 2026 Master Circular: who files, the nine principles, the nine BRSR Core attributes, assessment or assurance, and the value chain. Plus how to build data that survives assurance, the tricky KPIs, and what eight companies in the Above Average band of TERRA, Earth5R’s ESG intelligence platform, disclose. With four free templates.
What the guide covers
- Why BRSR matters more every year
- BRSR by numbers
- BRSR in one page
- The nine principles
- BRSR Core: nine attributes
- Assessment or assurance
- The value chain after March 2025
- What changed, 2021 to 2027
- Building the data system
- Ten steps to assurance readiness
- The tricky KPIs
- Best cases from TERRA
- Where BRSR meets the ground
- Seven common weaknesses
- A 12-month BRSR calendar
- Checklist for boards and CFOs
- Glossary of BRSR terms
Free templates
BRSR Core Data Workbook (Excel)
Nine sheets: which obligations apply to you this year, a KPI register with owners and evidence, a PPP intensity calculator, wages in smaller towns, openness of business, days payable and MSME sourcing, a value chain screener for the 2% and 75% thresholds, a 20-point readiness check and a calendar.
BRSR Reporting Manual (Word)
A model manual: regulatory basis, reporting boundary, roles, KPI owners, definitions and factors, data controls, restatement policy, value chain approach and assessment or assurance.
Value Chain Partner ESG Questionnaire (Word)
A cover letter and a short questionnaire covering energy, emissions, water, waste, people and safety, written so MSME suppliers can answer it.
Appointing a Provider (Word)
A selection checklist and scorecard, an independence declaration in SEBI’s terms, and a note to the Audit Committee and Board.
BRSR by numbers
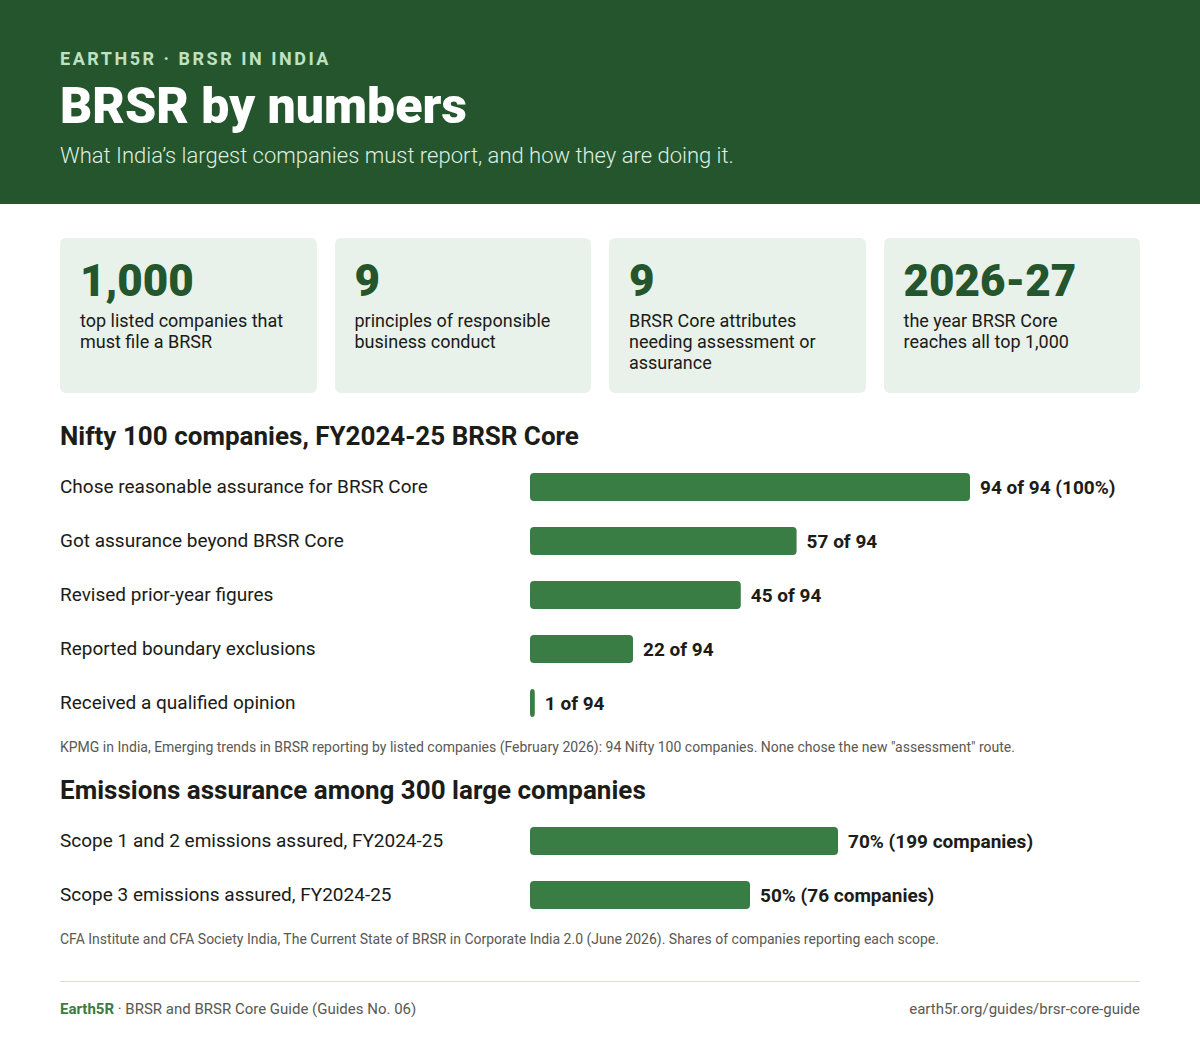
In KPMG’s review of 94 Nifty 100 companies for FY2024-25, all chose reasonable assurance for BRSR Core and none used the new assessment route; 45 revised prior-year figures, 22 reported boundary exclusions and 1 received a qualified opinion. Among 300 large companies studied by the CFA Institute, 70% had Scope 1 and 2 emissions assured in FY2024-25, but only 50% of those reporting Scope 3.
The nine attributes of BRSR Core
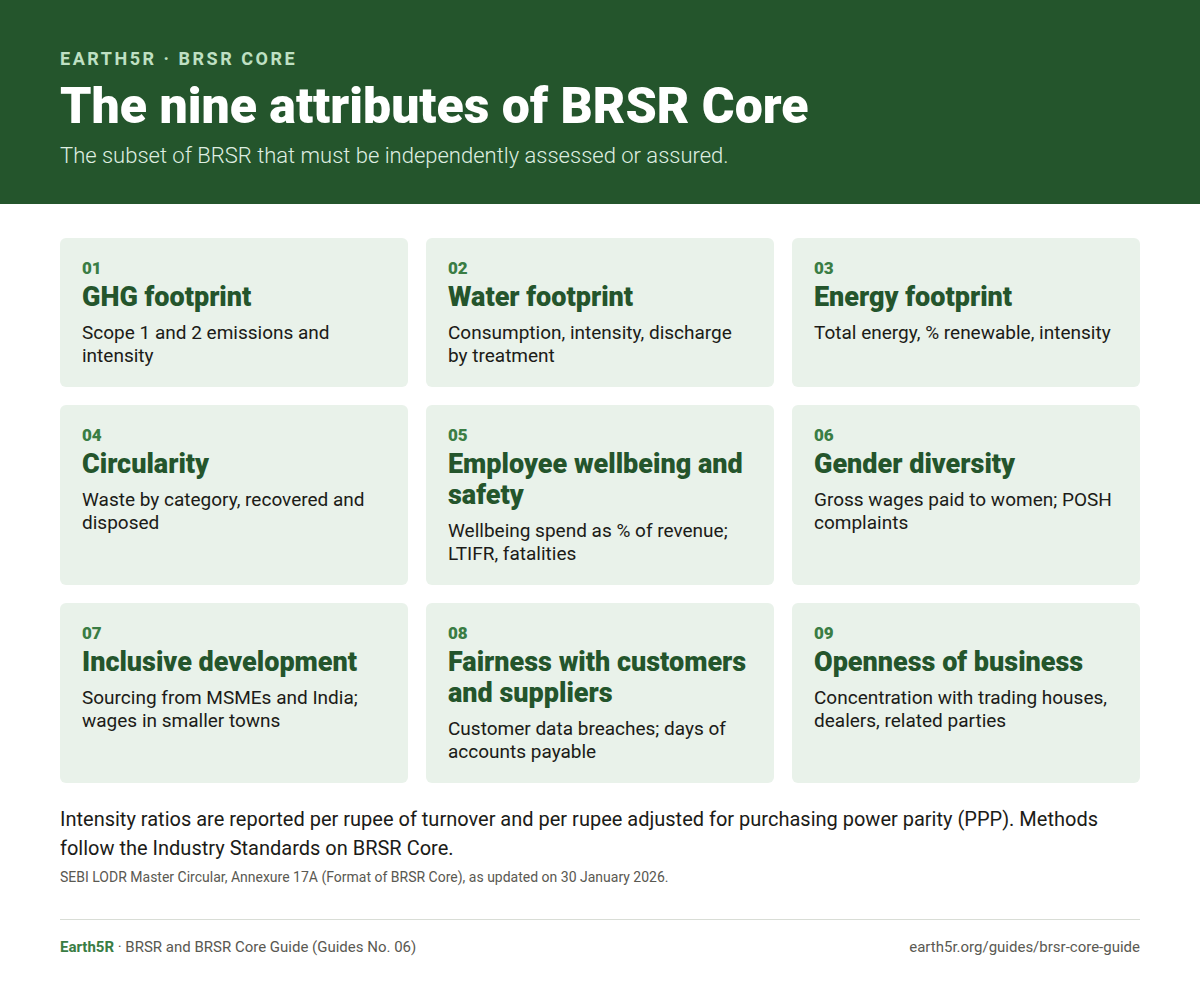
BRSR Core is the subset of BRSR that must be independently assessed or assured: GHG, water and energy footprints, circularity, employee wellbeing and safety, gender diversity, inclusive development, fairness with customers and suppliers, and openness of business. Intensity ratios are also reported per rupee of turnover adjusted for purchasing power parity.
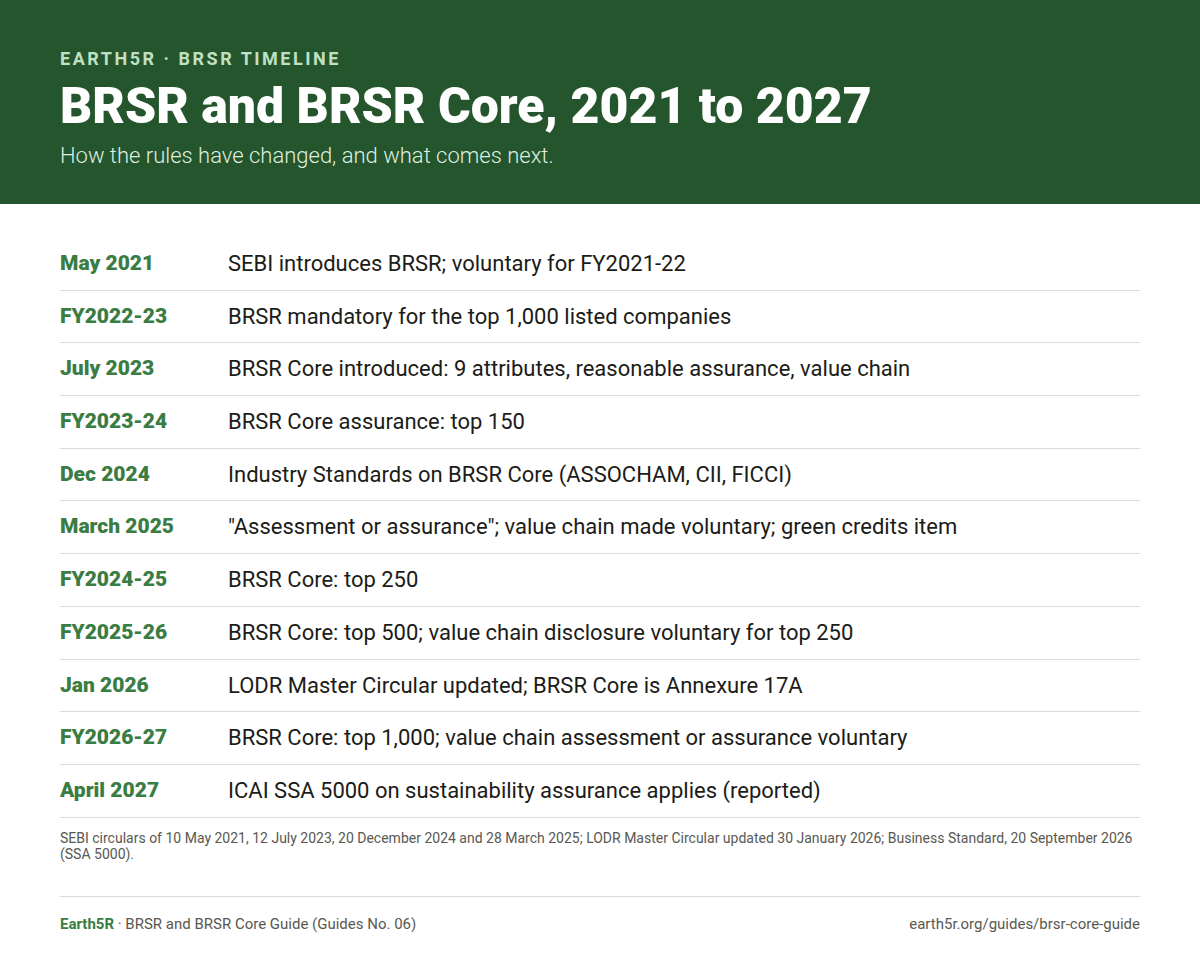
Assessment or assurance: the glide path
| Financial year | BRSR Core assessment or assurance |
|---|---|
| 2023-24 | Top 150 listed entities |
| 2024-25 | Top 250 |
| 2025-26 | Top 500 |
| 2026-27 | Top 1,000 |
Since the SEBI circular of 28 March 2025, companies may obtain either assurance or a third-party “assessment” under standards developed by the Industry Standards Forum. The provider must have the necessary expertise, and neither it nor its associates may provide consulting or other non-audit, non-assessment or non-assurance services to the company or its group.
The value chain after March 2025
| July 2023 framework | Current rule (March 2025) | |
|---|---|---|
| Who is a partner? | Top partners cumulatively making up 75% of purchases or sales | Partners individually at 2% or more of purchases or sales; coverage may be limited to 75% |
| Disclosure | Top 250, comply-or-explain, from FY2024-25 | Top 250, voluntary, from FY2025-26 |
| Assessment or assurance | Limited assurance, comply-or-explain, from FY2025-26 | Voluntary, from FY2026-27 |
BRSR and BRSR Core, 2021 to 2027
The tricky KPIs
- Intensity adjusted for PPP: state the factor and its source. FY2025-26 reports by HUL, Tata Steel and Infosys used 20.34.
- Wages in smaller towns: classify locations on a stated basis; HCLTech restated to RBI’s classification.
- Openness of business: use the Industry Standards definition of a trading house.
- Days of accounts payable: accounts payable × 365 ÷ cost of goods and services procured, tied to audited financials.
- Waste: disclose where vendor certificates are relied upon.
Best cases from TERRA
Each company below sits in the Above Average band of TERRA. We read their BRSRs and assurance statements for practices others can copy.
| Company | BRSR Core assurance | Worth copying |
|---|---|---|
| Hindustan Unilever | B S R & Co. LLP; reasonable on Core, limited on the rest; SSAE 3000 and SAE 3410 | Named boundary exclusions with a materiality reason; PPP factor disclosed |
| Tata Steel | PW & Co CA LLP; reasonable, standalone | Explains why overseas units are not yet in assured scope; consolidated Core figures disclosed voluntarily |
| HCLTech | DNV; reasonable on Core; ISAE 3000 and ISO 14064-3 | Restated smaller-towns data on the RBI basis; 308 value chain partners (76.4% by value) assessed for environmental impact |
| Infosys | Deloitte Haskins & Sells LLP; reasonable on Core | PPP-adjusted GHG intensity with the factor stated; 29.1% of wages paid to women |
| Dalmia Bharat | TÜV India; reasonable; ISAE 3000 | Revised prior-year figures under the Industry Standards, with the reason |
| Ashok Leyland | DNV; reasonable on Core | Training suppliers on BRSR Core with CII-CESD (64% of partners by value) |
| ABB India | TÜV India; reasonable; ISAE 3000 | A clear calendar-year basis; PPP-adjusted water intensity down from 0.72 to 0.60 |
| Persistent Systems | DNV; reasonable on the nine attributes | An explicit value chain goal at the 2% and 75% thresholds |
Seven common weaknesses, and the fix
| Weakness | Fix |
|---|---|
| Out-of-date rules | Read the current Master Circular each year |
| Silent boundary gaps | List exclusions with reasons and materiality |
| Unexplained restatements (45 of 94 revised in FY2024-25) | Restatement policy; disclose reason and effect |
| Definitions that drift | Follow the Industry Standards; document your basis |
| Unsupported vendor data | Check authorisations; reconcile; disclose reliance on certificates |
| Scope 3 left unassured (50% vs 70% for Scope 1 and 2) | Start with the largest categories and suppliers |
| Evidence built at year end | Half-year walkthroughs; maker-checker at source |
Cite or share this guide
ESG and finance teams, company secretaries, industry bodies, assurance professionals and universities are welcome to link to this page, add it to reading lists or training material, and embed the infographics. Please link to this page rather than the PDF, so readers always get the latest edition.
Questions
Is the BRSR and BRSR Core Guide free?
Yes. The guide, the BRSR Core Data Workbook (Excel) and the three Word templates are free to download without a sign-up, and free to share or adapt with credit to Earth5R.
Which companies must file a BRSR?
The top 1,000 listed entities by market capitalisation, mandatorily from FY2022-23, under Regulation 34(2)(f) of the SEBI LODR Regulations. Other listed companies may file voluntarily.
What is BRSR Core?
BRSR Core is a subset of BRSR key performance indicators under nine ESG attributes (Annexure 17A of the SEBI LODR Master Circular) that must be independently assessed or assured: GHG, water, energy, circularity, employee wellbeing and safety, gender diversity, inclusive development, fairness with customers and suppliers, and openness of business.
Which companies need BRSR Core assessment or assurance?
The top 150 listed entities from FY2023-24, the top 250 from FY2024-25, the top 500 from FY2025-26 and the top 1,000 from FY2026-27.
Is value chain disclosure mandatory under BRSR?
No. Since SEBI’s circular of 28 March 2025, value chain disclosure is voluntary for the top 250 listed entities from FY2025-26, and its assessment or assurance is voluntary from FY2026-27. Value chain partners are those individually at 2% or more of purchases or sales, and coverage may be limited to 75%.
What is the difference between assessment and assurance of BRSR Core?
Assurance is an independent engagement under assurance standards, at reasonable or limited level. Assessment is a third-party assessment under standards developed by the Industry Standards Forum in consultation with SEBI. In KPMG’s review of 94 Nifty 100 companies for FY2024-25, all chose reasonable assurance.
Can I use the infographics on my website?
Yes. Each infographic on this page has embed code. Please keep the credit link to this page.
Download the BRSR and BRSR Core GuideGet BRSR support from Earth5R